28/03/2011
Portuguese Government
The Socialist Portuguese Government fell last week as it failled to passover to the public the measures taken to reduce public spending. In fact what the politicians overlooked is the fact that the population of Portugal face a difficult situation caused by the Bankers and these same politicians. Unemployment well over the 11% Health care one of the worst and most expensive in Europe Education one of the worst in Europe Energy prices are one of the most expensive in the world (petrol, electricity, water, gas) Corruption according to local media is a daily happening Price fixing between companies for consumer goods and energy. The example of price fixing between energy companies happens on a weekly basis without no reason, the example shown by WorldWatch is the final consumer price motorists pay at the petrol pump, consumer prices go up everyweek, Last week petrol prices dropped in some cases by 2 cents per litre, only to increase this week by 2,5 cents in all companies working in Portugal, Galp, BP, Repsol and Cepsa. All these companies practice price fixing... This alone will further sink Portugals economy deeper into recession as the population have no money to support any growth. Petrol consumption will decline by 13% this year alone…

16/03/2011
The Socrates Affair.
 Portuguese bonds fell after Prime Minister Jose Socrates raised the specter of needing a bailout and Moody’s Investors Service cut the country’s debt rating.
The yield on 10-year debt rose 3 basis points to 7.44 percent and the spread, a measure of risk, widened 2 basis points to 429 more than comparable German bunds.
Opposition lawmakers’ resistance to additional budget cuts announced last week to meet deficit targets threatens a “political crisis,” Socrates said late yesterday in Lisbon. “The consequence of a political crisis is the worsening of the financing risks of our economy and would lead Portugal to
request external intervention.”
Portugal is fighting to avoid following Greece and Ireland in seeking a rescue. Socrates is raising taxes and implementing the nation’s deepest spending cuts in more than three decades, aiming to convince investors it can narrow its pay its bills on its own.
Portugal’s credit rating was cut two steps by Moody’s Investors Service yesterday to A3, four steps from so-called junk status, with the outlook on the grade “negative.” The rating company cited Portugal’s “subdued growth prospects” and “implementation risks for the government’s ambitious fiscal consolidation targets.”
Socrates became prime minister in 2005 and his Socialist Party won re-election in 2009 without a majority in parliament. Socrates is a power freek and uses all arguments to justify corruption in all spheres of government. One example of just how bad Socrates realy is ...this week the Socrates government reduced the sales tax from 23% to 6% on all activity that involves GOLF !!! on the other hand wants to increase some basic food items from 6% to 23%.The Social Democrats agreed in October to let the government’s 2011 budget proposal pass in parliament by abstaining.
The Portuguese debt agency plans to sell today as much as 1 billion euros ($1.4 billion) of 12-month bills. Borrowing costs increased at a March 9 auction of 1 billion euros of two-year bonds, which were sold at a yield of 5.993 percent, up from 4.086 percent at a previous auction of the same-maturity debt on Sept. 8.
Portugal intends to sell as much as 20 billion euros of bonds this year to finance its budget and cover the cost of maturing debt. Portugal faced bond redemptions next month and in June totalling about 9 billion euros. It faces bill maturities in March, July, August, September, October and November.
Finance Minister Fernando Teixeira dos Santos on March 11 presented additional deficit-cutting measures equal to 4.5 percent of gross domestic product over the three years through 2013, including a reduction in pensions of more than 1,500 euros a month and further cuts in tax benefits.
The additional measures were presented hours before European Union leaders agreed to allow the region’s temporary bailout fund to tap the entire 440 billion euros of lending capacity and to enable the rescue fund to buy bonds directly at issuance from debt-swamped governments.
The Portuguese government is already trimming the wage bill by 5 percent for public-sector workers earning more than 1,500 euros a month, freezing hiring and raising value-added sales tax by 2 percentage points to 23 percent to help narrow a deficit that amounted to 9.3 percent of gross domestic product in 2009, the fourth-biggest in the euro region after Ireland, Greece and Spain.
Portugal will report a 2010 budget deficit equivalent to 7 percent of GDP or less than 7 percent, narrower than the 7.3 percent gap the government had forecast,Socrates said on Jan. 28. The government has set a target for a budget deficit of 4.6 percent of GDP in 2011, and aims to reach the EU limit of 3 percent in 2012.
The Bank of Portugal on Jan. 11 said GDP will shrink 1.3 percent in 2011 as consumer demand drops and the government cuts spending. GDP contracted 0.3 percent in the final three months of 2010, the first quarterly contraction in a year. Portugal’s unemployment rose to 11.1 percent in the fourth quarter, the highest since at least 1998.
13/03/2011
Breaking Pictures: Destruction in Japan
 A JAPANESE man who was swept 15 kilometres out to sea by Japan's deadly tsunami was plucked to safety on Sunday after being spotted clinging to a piece of wreckage, officials said.
A Maritime Self-Defence Force destroyer rescued 60-year-old Hiromitsu Shinkawa after discovering him floating on a piece of roof in waters off Fukushima Prefecture, two days after the disaster struck.
The man, from the city of Minamisoma which has been virtually obliterated, was swept out along with his house after the massive tsunami tore into Japan's north-east following a 8.9-magnitude earthquake on Friday.
He is conscious and in 'good condition' after his rescue which took place around 12:40 pm (0340 GMT, 11.40am Singapore time), ministry officials said, adding that he was transported to hospital by helicopter.
'I ran away after learning that the tsunami was coming,' Shinkawa told rescuers according to Jiji Press.
'But I turned back to pick up something at home, when I was washed away. I was rescued while I was hanging to the roof from my house.' The government has said that at least 1,000 people are believed to have lost their lives in the disaster, and police estimate more than 215,000 people are huddled in emergency shelters...WorldWatch
05/03/2011


26/02/2011
Libyan crisis
 Saudi Arabia has raised oil output about eight percent to above nine million barrels per day (bpd) to make up for a near halt in Libyan exports, an industry source said, helping prices fall further from the highest since 2008.
Some European oil firms said they were looking to buy more crude from Iran and the West’s energy watchdog, the International Energy Agency, said on Friday there was no need for an immediate strategic stock release.
The Saudi move follows reassurances from Riyadh earlier in the week that it was prepared to act to prevent shortages as a result of the rebellion in Libya that has sharply reduced the fellow OPEC producer’s 1.3 million bpd of exports.
“We have started producing over 9 million barrels per day. We have a lot of production capacity,” the industry source familiar with Saudi production told Reuters. That would be up more than 700,000 bpd from January.
Top exporter Saudi Arabia is the only country able to pump large amounts of extra oil at short notice. It sometimes steps in unilaterally to meet shortages or when it feels prices have risen to levels that may threaten economic growth or oil demand.
The Organization of the Petroleum Exporting Countries has resisted calls for a formal increase in output and says it does not plan to meet until June.
Iran’s deputy Oil Minister Ahmad Ghalebani told the semi-official Mehr news agency he saw no need for an emergency OPEC meeting and that Iran would continue to comply with OPEC policy on quotas.
“There is no shortage of oil in the global crude market stemming from political turmoil in Libya and other North African countries that requires an increase of Iran’s oil exports,” Ghalebani told Mehr.
Brent oil prices jumped close to $120 a barrel on Thursday, the highest since August 2008.
News of Saudi Arabia’s higher output came as disruption to Libyan supplies worsened. Libya is the world’s 12th-largest oil exporter and a source of high-quality crude oil, most of which flows to Europe.
Libya’s crude exports have almost halted because of reduced production, a lack of staff at ports and security concerns, industry sources told Reuters earlier on Friday.
Other oil producers may also see increased demand as a result of the Libyan crisis.
Italy’s third-largest oil refiner, Saras, is looking to Russia, Iran and other Caspian countries to replace crude oil shipments from Libya, an executive said on Friday.
The International Energy Agency, which represents consumer countries, has said between 500,000 bpd and 750,000 bpd of crude, less than 1 percent of global daily consumption, had been removed “at present” from the market.
European oil companies have not taken up Saudi Arabia’s offer of more supplies yet, industry sources have said, with some saying Saudi crude would not be a suitable substitute for Libyan oil at their refineries.
In addition, they are not in need of extra supplies for now. The IEA said on Friday European refiners threatened by a shortfall had covered their needs well into March21/02/2011
Poor Economies
 One of the most expensive final consumer prices for petrol is in one of Europe’s oldest and most poor economies ...Portugal...
Filling a car with Regular 95 Octane is now a staggering 1,56€ per liter, until the start of the middle east unrest there was no need for the consumer petrol price to be inflated 20% above the real crude market price.
Portugal is in a recession that will be aggravated even further by rising prices which include, coffee, soft drinks, electricity, water and the announced 10% increase in the price of bread, not to mention that the petrol companies Galp.BP, Repsol and Cepsa inflate prices in a weekly basis according to the monopoly of the government and these same companies.
Petrol prices in Portugal are the most expensive ever, in a country were the unemployment passes the 11%, education is one of the worst in Europe, health care appalling, if this continues civil unrest will no doubt happen.
Dubai’s benchmark

Middle East shares continue to slump, sending Dubai’s benchmark stock index down the most this month, on concern political unrest in the region may spread and also the fact that OPEC have failed to control crude prices in the $85 per barril range,allowing speculation to once more affect the market.
Emaar Properties PJSC, builder of the world’s tallest skyscraper, dropped 4.7 percent. Dubai Islamic Bank PJSC, the United Arab Emirates’ biggest Shariah-compliant lender, fell the most since November.
The DFM General Index retreated 3.7 percent, the most since Jan. 30, to 1,536.45 at the 2
p.m. close in Dubai. Kuwait’s gauge tumbled 2.5 percent, led by Mobile Telecommunications Co. as the company’s board rejected all purchase offer for its 25 percent stake in Zain Saudi Arabia.
Arab governments are cracking down on pro-democracy activists as uprisings that toppled leaders in Tunisia and Egypt spread to Libya, Algeria, Yemen and Bahrain. Prince Talal Bin Abdul Aziz, a member of Saudi Arabia’s royal family, said on Feb. 17 that the kingdom may see protests unless King Abdullah Bin Abdul Aziz introduces reforms, according to BBC Arabic TV.
The spread of the geo-political tension into Bahrain is causing investors to be risk averse,the risk of spreading is dependent on each country’s situation. If you have a country with high inflation, an autocratic regime, high unemployment and a big percentage of the population that is below the poverty level and young, then the risk is high.
Bahraini protesters were considering the government’s offer of talks to resolve a conflict now in its seventh day as a Libyan opposition group warned of a “bloodbath” at the hands of security forces seeking to crack down on calls for political change sparked by Egypt and Tunisia.
Bahrain’s credit default swaps climbed 17 basis points to 304, the highest since July 2009 on Feb. 18, according to CMA prices in London. The cost of protecting Saudi Arabian debt against default for five years soared 12 basis points to 138, also the highest in 19 months. Swaps on Saudi Arabia are used as a measure of confidence in the country although they reference
no debt. The contracts pay the buyer face value in exchange for the underlying securities or the cash equivalent should a government or company fail to adhere to its debt agreements.
Subscribe to:
Posts (Atom)
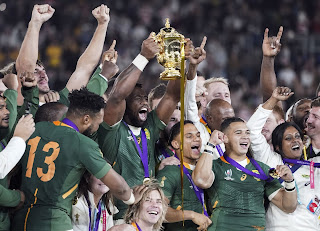
SOUTH AFRICA SPRINGBOKS
South Africa laid the groundwork with traditional Springbok rugby and finished an out-gunned England side off with two late tries to win ...
-
Crude oil declined to a seven-week low after a gauge of U.S. manufacturing showed growth at the slowest pace in two years, a sign the econ...
-
 Asian nations are grappling with record crude prices that have raised the cost of subsidies and caused losses for refineries. Indonesia and...
-
 News report from the WorldWatch agency confirms that crude consumption in Europe continues to decline as economies are in recession, this...